
USDA Loans: Zero Down in More Places Than You Think
USDA financing is not just for farms. Large parts of the map qualify, and the loan requires no down payment at all.
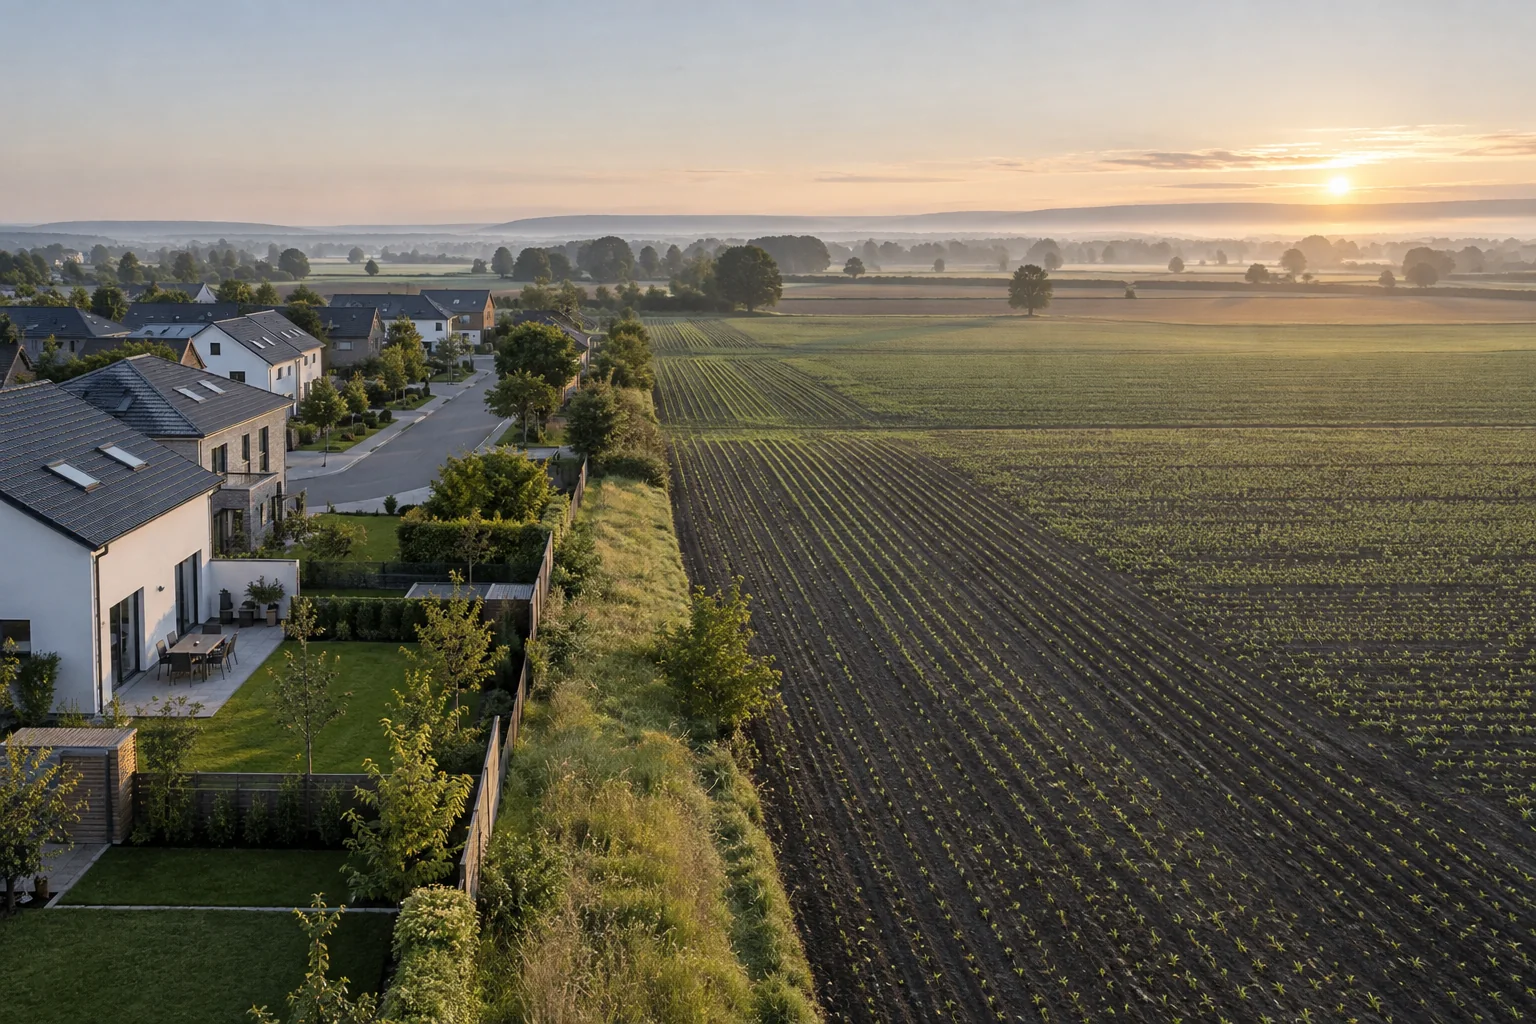
USDA rural development loans are the most overlooked program in residential lending. Buyers hear rural and picture a farm, when the eligibility map actually covers most small towns and a surprising amount of land just outside metro boundaries.
Two eligibility tests
The property must sit in a USDA-eligible area, which is checked by address on the program's map. And total household income must fall under the limit for that county and household size, which counts income from everyone living in the home, not only the borrowers.
Both tests are pass or fail, and both are worth checking before assuming you do not qualify.
How USDA and FHA compare on cost
USDA requires no down payment, compared with 3.5% for FHA. The annual guarantee fee is also typically lower than FHA's annual mortgage insurance premium, so the monthly payment on the same house is often lower too. Both figures reflect current program fees, which the agencies adjust periodically.
FHA is the better fit in several common situations: lower credit scores, properties outside USDA-eligible areas, and households whose income is over the USDA limit. The right answer depends on the borrower and the address, not on a blanket preference for either program.
Property requirements
The home must be a primary residence in generally sound condition, with working systems and safe access. Income-producing farm operations are not financed by this program, though a home on acreage frequently is. Appraisals follow standards similar to FHA.
Timeline
USDA files pass through a government guarantee step after lender approval, which can add days to the schedule depending on volume. Build that into your contract, and start the file early so the guarantee is requested the moment underwriting clears.
Does this apply to your situation?
Twelve questions, no credit check, and no email required. See which programs are commonly used for situations like yours.
Non-QM solves real problems, but it is not free. Here is how to tell whether you actually need it.
Lower credit, higher debt ratios, and 3.5% down. FHA is the most forgiving loan in the market, with one cost to understand.
Talk through your scenario.
Start an application or book a 20-minute call.